Starting Bigger Jobs in 2027? Check Your Public Liability Before You Sign
Taking on a bigger contract? Before you sign, check the public liability insurance requirements.
Another pair of hands can make a real difference.
Perhaps you’re taking on bigger jobs, bringing in an apprentice or getting some help during a busy spell. There’s plenty to organise before they start.
But alongside pay, equipment and training, there’s an insurance question to answer.
“Do I need Employers’ Liability insurance?”
It’s a sensible question whether you’re hiring your first employee or adding to an existing team. The short answer is yes, but it can depend on how someone works for you, not simply what you call them.
Most employers with employees normally based in Great Britain must have Employers’ Liability insurance, subject to certain very specific exemptions. GOV.UK says required cover must be in place as soon as you become an employer.
Our starting point is straightforward: tell your insurer or broker about everyone working in your business.
That includes family, friends, part-time and temporary staff, apprentices, volunteers and directors of limited companies. Their arrangements may differ, but none should be left out of the conversation.
These legal requirements concern England, Scotland and Wales. Businesses operating in Northern Ireland should check the separate HSENI guidance.
Being a sole trader describes your business structure. It does not mean you cannot employ people.
If you work entirely alone and employ nobody, you would not normally need compulsory EL insurance. Taking someone on should trigger a fresh check of your responsibilities. There are even circumstances where you will need EL for contractors.
Someone working only a few hours can still be an employee. The agreement does not have to be a written employment contract: it can be spoken or implied by the arrangement.
“We haven’t signed anything yet” is therefore not a reason to leave the insurance check until later.
Do not assume that someone helping you is outside your insurance responsibilities because you know them well.
Very rarely a family-business exemption can apply where all employees are qualifying close relatives. It does not extend to every relative or to friends, and it does not apply to family businesses incorporated as limited companies. Check the precise conditions before relying on it.
Include directors who work as employees when discussing EL cover.
A specific exemption applies where a company’s only employee owns at least 50% of its issued share capital. Being a director alone does not establish an exemption. Taking someone else on can change the position.
Calling someone “self-employed”, including for tax purposes, does not necessarily settle the EL question.
HSE highlights factors such as who controls the work, who supplies equipment and whether the person can send a substitute. These are indicators, not a simple test. Explain the arrangement to your insurer or broker, and seek legal advice if the person’s status is unclear.
People employed under a contract of apprenticeship fall within the Act’s definition of an employee. EL will normally be required unless an exemption applies.
Where an agency is involved, confirm who employs the apprentice and how insurance responsibilities are arranged. HSE identifies arrangements where an apprenticeship training agency is the employer.
Volunteers need separate consideration. Volunteering does not automatically make EL legally compulsory, although insurers will usually include volunteers within existing EL cover. Check the actual duties and policy arrangements rather than assuming unpaid help is covered.
HSE says as an employer taking on a young person for work experience, you have the main responsibility for their health and safety. If you have no EL policy, discuss the placement with your broker before it starts.
EL insurance is designed to cover an employer’s legal liability when an employee is injured or becomes ill as a result of your negligence when working for your business.
Depending on the policy, it can help with compensation and the legal costs of defending a claim.
Imagine an employee falls from a poorly maintained ladder. They allege that your business failed to provide safe equipment and bring a claim. EL insurance may respond, depending on the circumstances and policy terms.
For more on wellbeing and potential claims, see our guide to work-related stress and Employers’ Liability insurance.
There isn’t one price that fits every small business.
Insurers consider factors such as the size of the business, the work being carried out and the risks involved. Risk management might also influence the premium.
An office-based team and a team working on construction sites present different circumstances. A general price you see online may therefore tell you little about your own quote.
Have details of your workforce and their duties ready. Your broker will check the cover and conditions alongside the price.
Where EL is compulsory, the statutory minimum is £5 million, with cover from an authorised insurer.
That is the legal starting point. Your business’s risks may justify a higher limit, and HSE advises employers to consider whether more cover is needed.
Check any insurance requirements in client or main-contractor agreements too. If a contract specifies a higher amount, ask your insurer or broker whether your arrangements meet it before agreeing.
The main difference is whose claim the insurance is designed to address.
Having Public Liability insurance does not replace EL cover.
Our Introduction to Liability explains the different covers in more detail.
An employer can face a fine of up to £2,500 for each day without suitable required insurance. Failing to display the certificate, or refusing to provide it to HSE inspectors on request, can lead to a fine of up to £1,000.
There is also the potential cost of an uninsured claim. Without applicable cover, the business may have to fund legal costs and any compensation it owes.
An exemption from compulsory insurance does not itself remove potential liability.
Display your current EL certificate where employees can access it. Electronic display is allowed if they know where to find it and have reasonable access.
You’ve already got access to insurance support through your FSB membership. Register with FSB Insurance Service to unlock the support available to you, at no additional cost.
Our UK-based team can talk to you about your business insurance and the changes you’re planning.
Call 020 3883 7976 or register to unlock your included insurance support.
You don’t need to buy an insurance policy. Registration does not itself provide insurance cover.
This article provides general information, not personalised insurance or legal advice. Individual circumstances and insurance requirements vary. Cover is subject to the relevant policy terms, conditions and exclusions. Registration with FSB Insurance Service does not provide insurance cover.
Taking on a bigger contract? Before you sign, check the public liability insurance requirements.
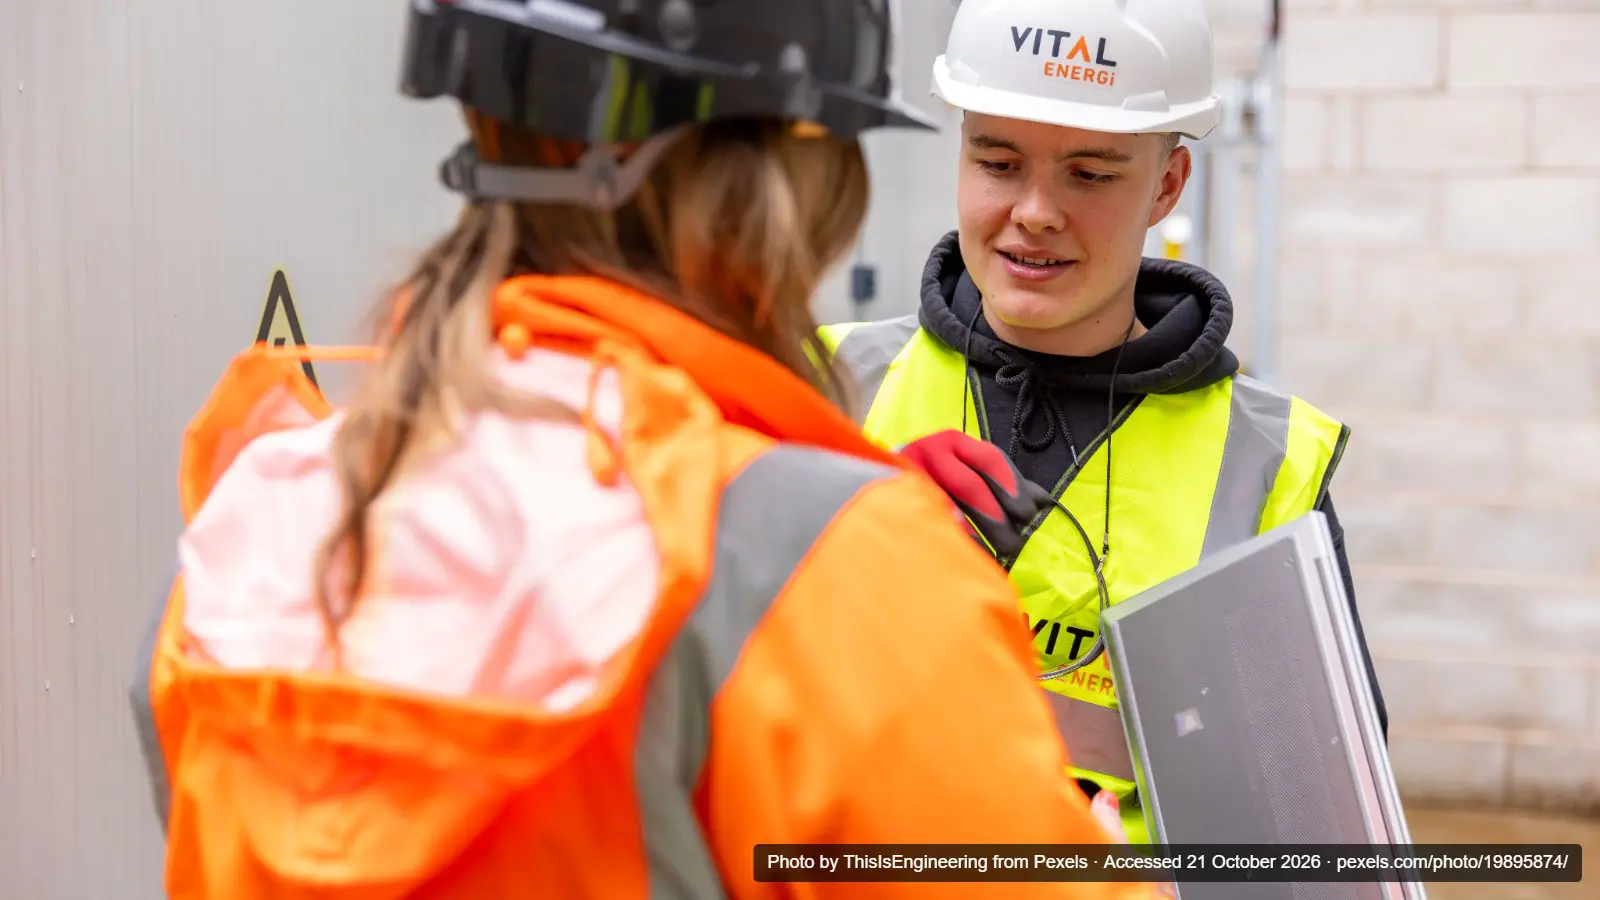
Taking on an apprentice could mean becoming an employer for the first time.

A difficult client conversation can quickly become a formal complaint or claim.